India’s recent Goods and Services Tax (GST) reforms have reshaped the apparel sector’s tax structure, benefiting mass-market clothing while increasing taxes on premium garments. However, the man-made fibre (MMF) segment continues to face challenges due to an unresolved tax imbalance in the polyester supply chain.
The reforms have addressed the long-standing inverted duty structure on man-made fibre and yarn, but a significant tax gap remains at the polyester feedstock stage. This imbalance could increase costs and create working capital pressures for manufacturers across the synthetic textile value chain.
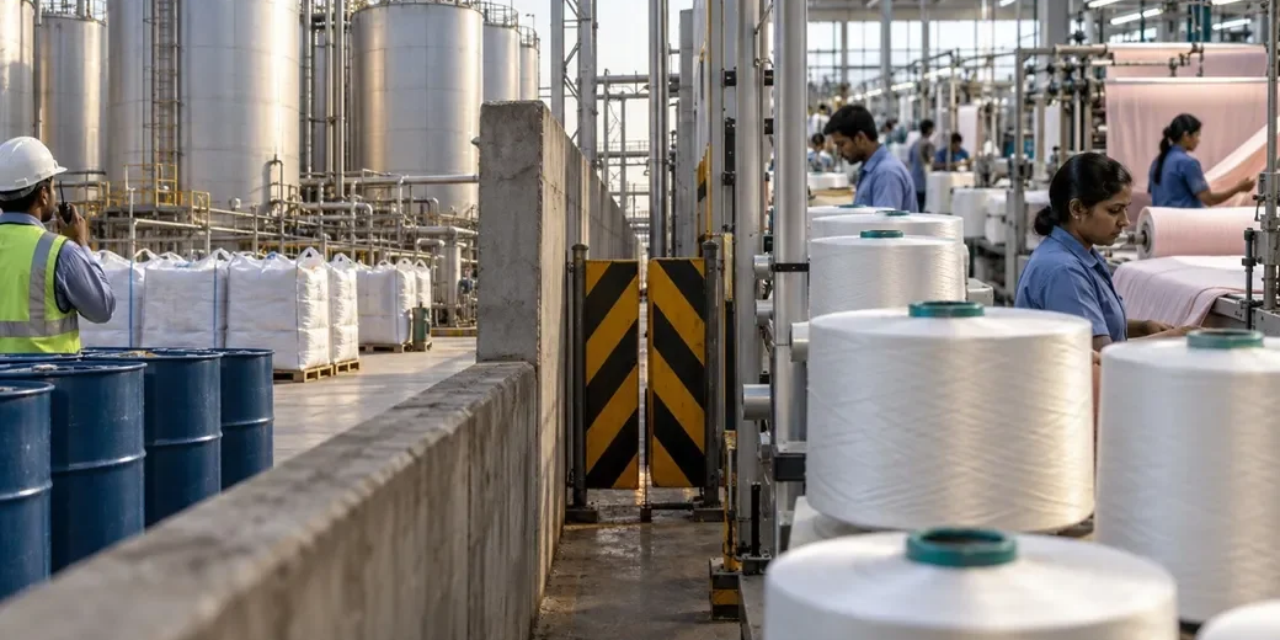
Polyester production depends on key raw materials, including purified terephthalic acid (PTA) and monoethylene glycol (MEG). Differences in GST rates between these inputs and downstream products can restrict manufacturers’ ability to fully offset input taxes, affecting cash flow and operational efficiency.
For textile manufacturers and exporters, the continued tax imbalance could weaken price competitiveness in domestic and international markets. Addressing the remaining inversion could help improve cost efficiency, support investment in man-made fibre production and strengthen India’s position in global textile value chains.

No comments yet. Be the first to share your thoughts!